Every month, a chunk of your salary leaves your account before you even notice it landing in another currency. Rent, groceries, your own savings goal — and right behind them, a transfer to your parents in India. For millions of NRIs, this is simply how the month works. It rarely feels simple, though.
Supporting family back home carries real financial weight. It also carries guilt, love, and long-term consequences that families rarely discuss out loud. This piece looks at what that support actually costs over time, why the amount tends to creep up, and how to plan for it without quietly draining your own future.
If you send money home every month, or expect to start soon, this is worth fifteen minutes of your time.
Ask ten NRIs how much they send home and you will likely get ten different answers, and ten different levels of confidence behind those numbers. Some have a clear monthly figure written into their budget. Others send “whatever is needed,” figured out on the fly whenever a call comes in. Neither approach is wrong on its own, but only one of them scales well over twenty or thirty years of working abroad.
Why This Conversation Feels Different for NRIs
Financial support within a family is not new. What changes once you move abroad is the scale and the distance. You are budgeting in one currency while your obligations sit in another. Exchange rates shift the value of what you send without warning. And you cannot always see, day to day, what the money is actually being used for.
On top of that, family financial planning NRI households deal with is rarely a single, one-time decision. It is an open-ended commitment that can run for decades — through a parent’s retirement, an illness, a sibling’s wedding, or a home repair that suddenly cannot wait.
None of this makes the support wrong. It just makes it something that deserves a plan, not just good intentions.
There is also a generational layer to this. Parents who grew up managing money in cash, within a single city, are now depending on a system of wire transfers, exchange rates, and foreign bank apps they may not fully follow. That gap in understanding can create friction — a parent who feels short-changed by a transfer that, after fees and conversion, is smaller than expected, even though the sender did nothing wrong.
What Supporting Family Back Home Actually Costs
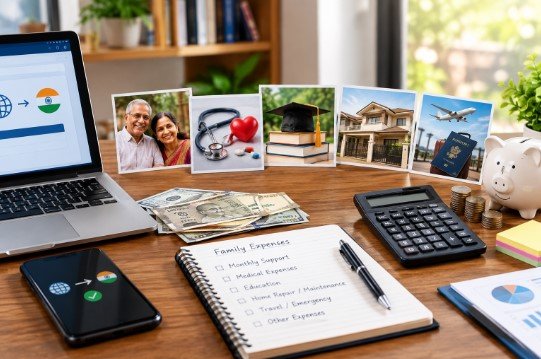
Monthly Remittances vs One-Time Big Expenses
Most NRIs experience two very different types of outflow:
- Recurring support — a fixed or semi-fixed amount sent monthly or quarterly for parents’ living expenses, medicines, or household help.
- Lump-sum events — a wedding, a hospital admission, a property repair, or an education fee that arrives with little warning and needs a large amount fast.
Recurring transfers are easier to plan for because they are predictable. Lump-sum events are the ones that derail personal savings, because they often compete directly with an NRI’s own emergency fund or retirement contribution.
The Hidden Costs Nobody Budgets For
Beyond the transfer amount itself, families often underestimate:
- Currency conversion losses and transfer fees that quietly eat into every remittance.
- Inflation in India, which can outpace the exchange-rate benefit an NRI assumes they are getting.
- The cost of flying back for emergencies, which is rarely built into any budget.
- Property and asset upkeep — taxes, maintenance, or legal fees on a family home nobody currently lives in.
A closer look at transfer costs and account structures is covered in DeshSansaar’s NRI banking and remittance guide, which breaks down account types and where money quietly leaks out during a transfer.
Want the full picture on money, property and compliance as an NRI?
How Currency Swings Change What Actually Reaches Home
A number that feels stable in your paycheck currency can behave very differently once it lands in India. A weaker rupee sometimes works in an NRI’s favour, stretching each transfer further. A stronger rupee does the opposite, quietly shrinking the value of a fixed monthly amount without anyone changing a single habit.
Families who treat the remittance amount as a fixed number in their own currency, rather than a fixed value in rupees, tend to avoid a common source of confusion: a parent wondering why “the same amount” suddenly covers less than it used to. Reviewing the actual rupee value received every few months, not just the number sent, closes that gap.
This is also where transfer method matters. Bank wires, remittance apps, and forex cards all price currency conversion differently, and the spread between them can be larger than most people assume over a full year of transfers.
Common Financial Pressure Points for NRIs
Parents’ Medical and Elder Care Needs
Healthcare is usually the single largest and least predictable expense. A parent’s fall, a cardiac scare, or a planned surgery can turn a calm month into a financial scramble. Families who plan ahead — getting a realistic cost estimate before treatment rather than after admission — tend to handle these moments with far less panic.
For families weighing a planned procedure for a parent in India, getting a treatment planning and cost estimate before booking anything can prevent a lot of the financial guesswork that usually happens after admission, when there is far less room to negotiate or compare options.
Siblings’ Education or Life Events
Education fees, weddings, and starting-out costs for younger siblings often land on the NRI family member by default, simply because their income looks larger in rupee terms. This assumption is not always fair, and it is worth naming clearly within the family rather than absorbing quietly.
It also tends to compound. One wedding contribution can quietly set an expectation for the next family event, and the next, without anyone formally agreeing to it. Naming a one-time gift as exactly that — a one-time gift — helps keep future events as separate decisions rather than an assumed pattern.
Property Upkeep and Legal Obligations
An ancestral home or inherited property comes with taxes, repairs, and paperwork that someone has to manage from a distance. DeshSansaar’s property and inheritance guidance walks through the documentation NRIs commonly overlook until it becomes urgent.
Building a Realistic Family Support Budget
Step 1: Separate Needs From Wants
Sit down — ideally with your parents or a sibling — and separate genuine living costs (medicine, groceries, utilities, household help) from discretionary spending. This single exercise removes a surprising amount of tension, because it turns a vague sense of obligation into a concrete, shared number.
Step 2: Set a Ceiling, Not a Blank Cheque
An open-ended promise to “help whenever needed” sounds generous, but it leaves no room for your own financial planning. A monthly ceiling, reviewed once or twice a year, protects both your family’s needs and your own long-term goals.
Step 3: Automate What You Can
Standing instructions for recurring transfers reduce decision fatigue and missed payments. Keep a separate account or sub-account purely for family support, so it never mixes with your personal savings or investment contributions.
Not sure where to start with the numbers?
The Emotional Side of Financial Obligation
Money sent home rarely stays purely financial. It gets tangled with guilt about living abroad, pressure to prove success, and old family dynamics that migration does not erase. Some NRIs over-send to manage guilt. Others under-communicate because money conversations feel uncomfortable, which then creates confusion at home about what to expect.
This overlap between money and emotion is real enough that DeshSansaar has a dedicated look at emotional and guilt-driven financial decisions many NRIs quietly carry — worth reading if remittance decisions feel heavier than the numbers alone would suggest.
Practical Ways to Reduce Remittance Strain
Understand Your Banking Options
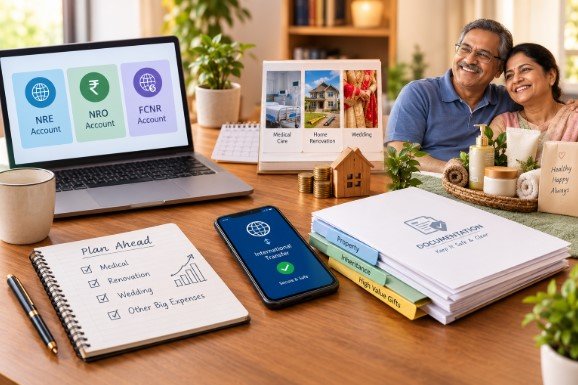
NRE, NRO, and FCNR accounts each serve different purposes, and picking the wrong one can mean unnecessary tax exposure or repatriation restrictions later. This is one of the most common — and most fixable — mistakes in family financial planning NRI households make early on.
Plan Big Expenses Ahead of Time
Where possible, treat predictable big-ticket items — a planned surgery, a home renovation, a wedding — as projects with their own mini-budget and timeline, rather than emergencies. A little lead time changes the entire negotiating position, whether that is with a hospital, a contractor, or a bank.
Keep Documentation Clean
Every transfer connected to property, inheritance, or high-value gifts should be documented as it happens. DeshSansaar’s NRI tax basics guide covers how residency status and reporting obligations interact with money moving between countries, which is worth understanding before, not after, a large transfer.
Some families also quietly set aside a small monthly amount for a parent’s everyday wellness — skin, hair, and general self-care essentials that are easy to overlook once healthcare costs take priority. Choosing natural, toxin-free skincare and haircare essentials for parents is a small, low-cost way to fold that kind of care into a family support budget without it becoming another unplanned expense.
Facing a medical decision for a parent in India?
When Family Support Turns Into Financial Risk
There is a line between generous support and financial self-harm. Warning signs include dipping into retirement savings repeatedly, taking on debt to cover remittances, or avoiding your own medical or insurance needs to keep sending money home. None of these make the support more meaningful — they just move the financial stress from one generation to the next.
A useful gut check: if a friend described your exact remittance pattern to you, would you call it generous, or would you gently tell them to slow down? Outside perspective tends to be more honest than the view from inside an ongoing family obligation.
If property, inheritance, or long-term planning is part of what is driving the pressure, DeshSansaar’s NRI planning and compliance guide is a useful next step for mapping obligations before they compound.
A Simple Framework to Revisit Every Year
Once a year — perhaps around a visit home or a family milestone — run through four questions:
- Has the actual cost of supporting my family changed in the last twelve months?
- Am I still comfortable with the current monthly ceiling?
- Is there a big expense on the horizon I should start planning for now?
- Am I protecting my own savings and retirement at the same time?
Answering these honestly, even briefly, keeps support sustainable instead of reactive.
Bottom Line
Supporting family back home is one of the most consistent financial commitments in NRI life. It works best when it is treated as a plan with numbers and limits, not an open-ended promise. A clear budget, honest conversations, and a little advance planning protect both your parents’ comfort and your own financial future.
Want to understand how remittances and residency status interact?
FAQs:
There is no fixed number. Base it on parents’ real costs, not income comparisons.
Money sent for parents’ maintenance is generally not taxed as their income.
It depends on the purpose — NRE, NRO, and FCNR accounts each serve different needs.
Keep a separate emergency fund and get cost estimates before, not during, treatment.
Set a clear, honest ceiling early. Silence usually creates more conflict than numbers do.